What Out-of-State Movers to Houston Need to Know Before Day One
Every national guide covers the no-income-tax pitch and warns you about traffic. This one covers the 30-day vehicle registration clock, MUD tax sticker shock, how to check flood risk before you sig…
Every national guide covers the no-income-tax pitch and warns you about traffic. This one covers the 30-day vehicle registration clock, MUD tax sticker shock, how to check flood risk before you sign a lease, and why homeowners insurance in Harris County is a genuinely different game than anywhere you’ve lived before.
October is when corporate HR departments start issuing Q1 transfer letters. Families are figuring out whether to land in Harris County, Fort Bend, or Montgomery County, and whether their kids can start at a new school in January. National relocation content dominates the search results. Almost none of it helps.
The same five clichés cycle endlessly: no state income tax, bad traffic, oppressive humidity, world-class BBQ, impossible sprawl. All true. None of it tells you what happens on Day 1, Day 30, or in the forty-five minutes before you sign a lease on a house in Cypress that sits inside a MUD district you’ve never heard of.
This guide covers the operational layer of moving to Houston. It assumes you’ve already decided to come. What it gives you is specific process detail—the right databases, the right deadlines, the questions to ask before you’re legally or financially committed. Most people only learn this stuff after they needed it.
One geographic note before we start: when people say “Houston,” they typically mean a metro spanning Harris County and six surrounding counties. Which county you land in changes your property tax rate, your school district, your flood control district, and which appraisal database you’re searching. This guide focuses primarily on Harris County and the areas people most commonly mean when they say they’re moving to Houston: the Katy corridor, Pearland, Cypress, and the city proper. Where county lines matter, we’ll say so.
Check Flood Risk Before You Sign Anything
Do this before you commit to an address. Before you fall in love with a house in Meyerland. Before you sign a lease in the lower blocks of Brays Oaks. Before almost everything else on this list.
Houston’s flood risk is hyper-local in ways that genuinely don’t translate from other cities. The standard tool most people reach for is FEMA’s Flood Map Service Center at msc.fema.gov. Look up any address and you’ll see its official flood zone designation. Zone AE means the property sits within the 100-year floodplain—roughly a 1% annual probability of flooding in any given year. Zone X is FEMA’s lower-mapped-risk designation. These are useful reference points, but the maps carry a documented lag problem: federal updates are infrequent, and Houston’s development and drainage patterns change faster than the federal government tracks them. That gap has cost people here real money.
The Harris County Flood Control District maintains a more current tool. Its interactive map overlays post-Harvey inundation data, historical high-water marks, and drainage project status. The district’s main site is hcfcd.org. Verify the current URL for the flood viewer directly there, since web tools get migrated. If the viewer is temporarily down, HCFD staff can walk you through the data by phone.
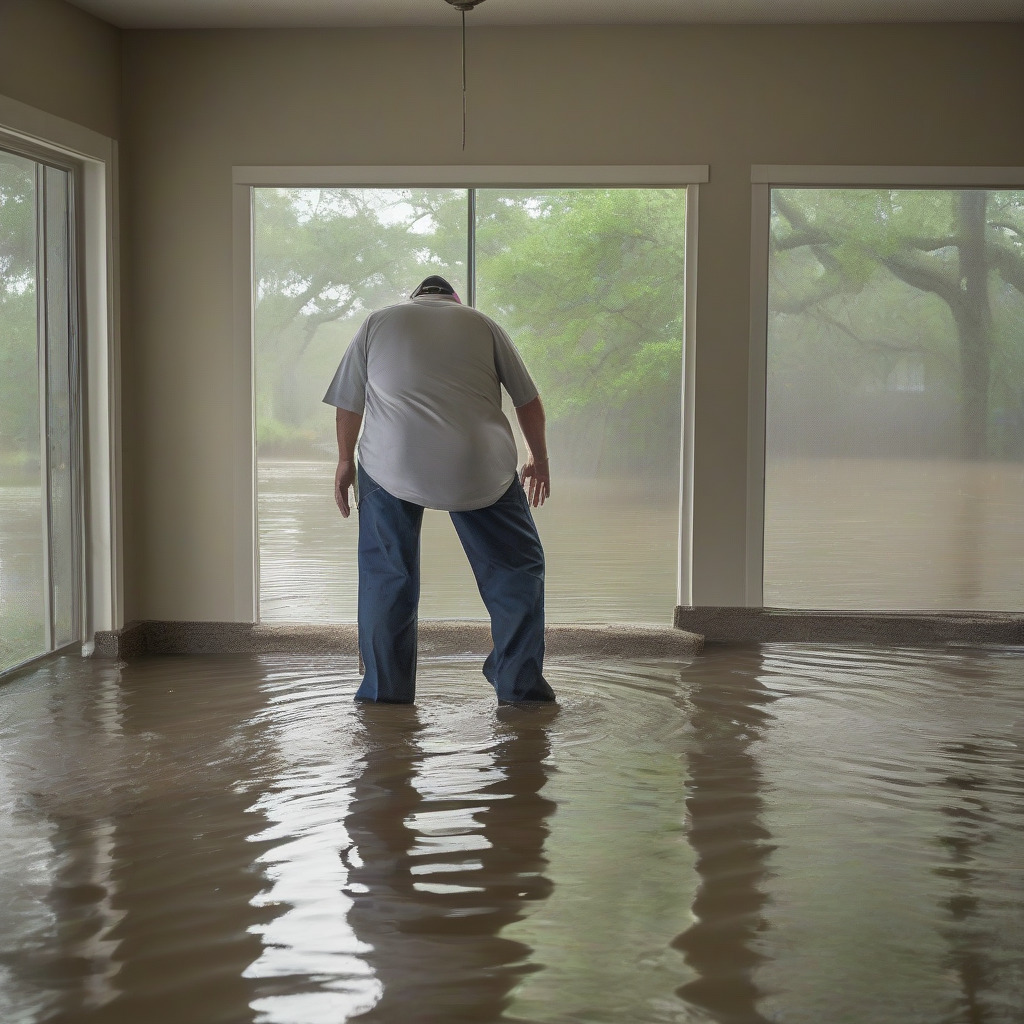
Use both tools. A Zone X designation is not a guarantee of dry floors. The 2015 Memorial Day Flood and the 2016 Tax Day Flood both inundated structures FEMA maps showed as lower-risk. Pay particular attention to Meyerland, which flooded in 2015, 2016, and 2017—three consecutive years; the Brays Bayou corridor from Westbury to the Medical Center; lower-lying sections of Montrose near Buffalo Bayou; and the Addicks and Barker reservoir spillways in the Katy/Bear Creek area. In Harvey, the Army Corps of Engineers released water from those reservoirs to protect the city center, flooding thousands of homes that had never flooded before. That’s the kind of detail that doesn’t make it into the national relocation guides, and it matters enormously if you’re looking at anything west of Beltway 8.
Texas law requires sellers to disclose prior flood claims on a residential disclosure form. Ask anyway, explicitly, and get any answer in writing. Rental disclosure obligations are narrower than seller disclosures, so if you’re renting, the question falls entirely to you.
Flood insurance is a separate policy from homeowners insurance. Standard homeowners policies do not cover flood damage. No exceptions. If a property is in Zone AE, your lender will require flood insurance. If it’s in Zone X, you can choose to carry it or not—but given Houston’s track record, a lot of residents do. The National Flood Insurance Program sets base rates, but private carriers now compete in the Texas flood market and sometimes offer better pricing on higher-value homes. Don’t make this call at closing under time pressure.
What a MUD Tax Is and Whether You’ll Owe It
If you’re buying in Katy, Pearland, Cypress, League City, Sugar Land, or The Woodlands, you will almost certainly be paying a Municipal Utility District tax. Writers who’ve never lived here don’t know to look for it, which is why it doesn’t appear in most relocation guides. I’ve talked to buyers who found out at the closing table. Don’t be that person.
Here’s how it works. When a developer builds a subdivision in unincorporated land outside city water and sewer service, they need to finance the water treatment plant, sewer lines, and drainage infrastructure from scratch. Texas law lets them create a special taxing district—a Municipal Utility District—that issues bonds to pay for that infrastructure. Homeowners within the MUD boundaries repay those bonds through an additional property tax levy, stacked on top of whatever they owe to the county, school district, and any applicable city. Harris County has more than 900 active MUDs—more than any other county in the country.
The rate range is wide enough to matter. MUD taxes typically run from around $0.10 to over $1.50 per $100 of assessed value, depending on how much debt the district originally issued and how much has been retired. On a $400,000 home, that swing runs from $400 to over $6,000 per year in MUD taxes alone, layered on top of your county, school district, and city rates. Factor this in before you make an offer. For a broader look at what property owners in the area often overlook, our moving & real estate coverage goes deeper on the financial details of landing in the Houston metro.
MUD rates decline over time as bonds are retired. A subdivision built in the mid-1990s in Cy-Fair or Katy may be approaching a near-zero MUD rate today—those 30-year bonds are nearly paid off. A brand-new community carries the full debt load. Comparing a new-construction home to a resale in an older Katy subdivision requires you to account for where the MUD is in its lifecycle, not just its current rate. A new home at $1.20 today could see that drop significantly over a decade of ownership. The resale in an older district may already be at $0.15 and falling. Neither is obviously better; it depends on how long you plan to stay. But you need to model it before negotiating price.
To look up a specific property’s MUD district, pull the address at hcad.org. The tax rate breakdown on the HCAD record lists associated taxing entities, which may include a MUD designation by name or number. If you’re uncertain whether you’re reading the record correctly, call the district directly or ask your title company to confirm. For properties outside Harris County: Fort Bend CAD (fbcad.org) for Sugar Land and Missouri City, Brazoria CAD for Pearland, Montgomery CAD for The Woodlands area.
Texas requires a MUD disclosure notice before closing on a purchase. Read it. It names the district, states the current tax rate, and lists the outstanding bond balance. If you’re seeing it for the first time at the closing table, you’ve already lost the ability to factor it into your offer. Ask your buyer’s agent to pull the disclosure and current rate before you go under contract.
Registering Your Car in Harris County: The 30-Day Clock
Texas has no DMV in the sense most states do. Vehicle registration is handled at the county level. In Harris County, that’s the Harris County Tax Office, Motor Vehicle Division, which operates multiple branches across the county. Verify current branch addresses, hours, and Saturday availability at tax.hctx.net before you go.
The 30-day clock is real and enforced. Texas law requires new residents to title and register within 30 days of establishing residency—and here’s where people trip up. The clock starts not when your moving truck arrives but when you take actions that demonstrate intent to live here. Signing a lease. Accepting employment. Enrolling children in school. If you signed a lease in October, the clock started in October.
First step: get a Texas vehicle safety inspection. You can’t register without a passing certificate from a Texas-licensed inspection station. Most auto repair shops, many gas stations, and dedicated inspection centers are licensed. Bring your current registration and proof of insurance.
Then gather your documents before going to the tax office: the out-of-state title (or lender payoff and lien information if the vehicle is financed), a Texas insurance card from a Texas-admitted carrier, your passing inspection certificate, and payment. Your current out-of-state insurer may or may not be admitted in Texas—confirm this before you go, because showing up at the window with the wrong paperwork means making the trip twice. Verify the current fee schedule at txdmv.gov before your visit.
The title transfer and registration happen in one transaction. This surprises people who’ve lived in states where they’re separate processes. You’re simultaneously transferring the out-of-state title to a Texas title and registering the vehicle—one window, one visit. Online renewal is available in subsequent years, but the initial Texas title transfer requires an in-person visit. Budget a morning for it, especially at a higher-traffic branch. Multiple vehicles can typically be processed in the same visit.
Enrolling Kids Mid-Year in HISD, Katy ISD, or Cy-Fair ISD
Mid-year school enrollment is the highest-anxiety logistics task for relocating families, and there’s one piece of Texas law worth knowing immediately: schools must provisionally enroll a transfer student within 25 days while waiting for records to arrive from the out-of-state school. A Texas school cannot deny enrollment because your child’s transcripts haven’t arrived yet. Verify the current statutory language at tea.texas.gov, but this provision has been longstanding policy. Do not let a campus registrar tell you enrollment must wait for records.
HISD serves the city of Houston proper. Mid-year enrollment for families moving into a zoned attendance area is handled primarily at the campus level. Find your zoned campus using the address lookup at houstonisd.org, then contact that campus directly. Required documents typically include proof of residency (signed lease or utility bill), immunization records, birth certificate, and any available prior school records.
For families interested in HISD’s magnet programs: mid-year entry is generally frozen. Magnet applications go through an annual lottery. Mid-year slots are rarely available, and families who arrive expecting to walk into a magnet program mid-semester are almost always disappointed. Enroll at your zoned campus first, establish residency, and apply for a magnet transfer for the following school year. Current magnet application timelines are at houstonisd.org/magnet.
Katy ISD covers portions of Harris, Fort Bend, and Waller counties. This one genuinely trips people up: a significant number of addresses with a “Katy, TX” mailing address actually fall within Cy-Fair ISD boundaries. The mailing address tells you nothing. Run your specific address through the attendance zone lookup at katyisd.org before contacting anyone.
If your address confirms as Katy ISD, mid-year enrollment is processed through the district’s Education Support Complex. Verify current address, hours, and any online pre-registration requirements at katyisd.org before visiting.
Cy-Fair ISD serves northwest Houston and the Cypress area. Mid-year transfers are generally processed at the individual campus. Confirm your attendance zone at cfisd.net, then contact the campus registrar directly. Required documents are the same as HISD.
If you’re arriving in December for a January semester start, don’t wait until the first week of January. Campus registrars at large suburban ISDs are managing dozens of mid-year arrivals in early January. A signed lease is typically sufficient as proof of residency. Start the paperwork in December, before you’re fully unpacked.
Why Homeowners Insurance in Harris County Is a Different Conversation
If you’re buying a home here and you’re coming from Colorado or Ohio, the homeowners insurance market operates differently than most of the continental U.S. More expensively and with more friction. Budget for it before closing, not after.
Harris County’s exposure to hurricane wind damage, flooding, and hail has made it a difficult market for insurers for decades. That difficulty accelerated sharply after Hurricane Harvey in 2017—approximately 300,000 flood claims were filed in Harris County alone—and accelerated again as national carriers began contracting their catastrophe exposure in the early 2020s. Several major carriers, including State Farm and Allstate, have significantly restricted new policy issuance in the Houston market, reduced coverage terms, or declined to renew existing policies. Coverage is still available. Getting it takes more work, and it costs more than you’re probably expecting.
Many Harris County homeowners are paying $3,000 to $6,000 or more annually on a mid-range home, depending on location, construction type, roof age, and proximity to the coast. Get a real quote from an independent agent before you go under contract on any home. The annual premium difference between two comparable homes in different flood zones, or with roofs of different ages, can easily swing your total cost of ownership calculation.
The roof is the dominant underwriting variable in this market. Insurers scrutinize roof age and condition more aggressively than almost anything else. A home with a roof older than 10 to 15 years may be declined by standard carriers or offered only with high deductibles. In a competitive purchase, asking for a roof inspection isn’t just due diligence—it’s directly tied to your ability to insure the property at a rate your lender will accept. Knowing what a Houston home inspection should cover that many inspectors skip can help you flag roofing and drainage issues before they become insurance problems.
Wind and hail deductibles are not the same as your standard deductible. Most Texas homeowners policies carry a separate wind and hail deductible that is typically much larger than the flat dollar amount that applies to other claims. Confirm the specific deductible structure with your insurer before you close. This is the detail that surprises nearly every out-of-state buyer, always at the wrong moment.
If you’re declined by standard carriers, the Texas surplus lines market offers coverage through insurers authorized to write non-standard business through licensed surplus lines agents. Premiums are generally higher and terms less predictable, but coverage is available. Work with an independent agent who writes both admitted and surplus lines business. A captive agent for a single carrier can’t shop the full market for you, and in this market, that limitation is a real problem.
Homes within the Texas Windstorm Insurance Association eligibility zone—primarily coastal counties—have a separate wind and hail policy pathway. Harris County’s TWIA eligibility status should be verified directly at tdi.texas.gov for any specific property. Most of Harris County is not in the TWIA primary zone, but don’t assume.
One More Detail: Q4 Lease Concessions and Where to Look
If you’re renting while you figure out where to buy—a reasonable approach in a metro this size, and one I’d genuinely recommend—October through January is historically a better period to negotiate lease terms. Apartment communities in Midtown, Montrose, and the Energy Corridor regularly extend Q4 concessions: multiple weeks free on 12- to 14-month leases, reduced security deposits, waived application fees. The Energy Corridor market, west along I-10 roughly from Beltway 8 to Highway 6, tends to move with the oil and gas hiring cycle. Leasing traffic that peaked in spring and summer thins out by Q4. Ask directly about concessions rather than waiting for them to appear in the listing. They’re frequently available and frequently unadvertised.
Montrose and the Museum District are the most relevant neighborhoods for arrivals wanting walkability and proximity to the Texas Medical Center. The Energy Corridor is the practical choice for anyone working in oil and gas or at one of the major corporate campuses out there. Katy and Cypress make geographic sense for families prioritizing the school districts covered above—but confirm any apartment you’re considering is in your target ISD attendance zone before you sign. A single street can change the district, and landlords don’t always know this. Some do know and don’t volunteer it.
The Short Version, Before You Close the Tab
Run every address through both FEMA’s flood map tool and the Harris County Flood Control District viewer before you sign anything. Ask about prior flooding directly, regardless of what the maps show.
Before making an offer on a suburban home, look up the MUD district at hcad.org, find the current rate, and figure out where that district is in its bond lifecycle.
Within 30 days of establishing residency, get your Texas vehicle safety inspection first, then take your out-of-state title and Texas insurance card to a Harris County Tax Office branch. One trip, one transaction.
Once your lease is signed, start the school enrollment process immediately—use the district’s address lookup tool to confirm which ISD your address actually falls in before you contact anyone.
Before going under contract on a home, get a homeowners insurance quote. Confirm the roof age. Understand that your wind and hail deductible is a separate, larger number than your standard deductible.
None of this is complicated once you know it exists. The people who have a rough first year in Houston aren’t the ones who found the city hard. They’re the ones who assumed it worked like wherever they came from.